

Bill Payment Reminder, Budgets

- 7.71K Reviews
- 4.5
- Downloads
- 1,000,000+
Our take on Bill Payment Reminder, Budgets from Appgk
Managing bills sounds simple until several due dates, payment methods, and household responsibilities start competing for attention. I found Bill Payment Reminder, Budgets useful because it approaches that everyday problem as a finance app rather than trying to become a full banking replacement. It gives me a place to organize reminders, monitor planned spending, and keep a clearer view of recurring obligations. That focus makes it easier to understand what the app is for: it is a planning and tracking tool, not a substitute for checking each payment with the relevant bank or service provider.
The app is developed by TimelyBills and is available free of charge, with optional in-app purchases ranging from $0.99 to $64.99 per item. It is rated for Everyone, which fits the straightforward household-money focus, and it runs on Android starting with version 8.0. The current version is 1.26.027. Its broad reach is also notable: it has passed one million installs and holds a 4.5 average from around 37 thousand ratings, alongside roughly 7.7 thousand written reviews. Those figures suggest that the basic reminder concept has found a substantial audience, although popularity alone is not a reason to hand over financial information without thinking carefully about what I actually need.
What the app feels like in everyday use
My first impression is that the most useful way to approach this app is to treat it as a financial calendar with budgeting support. Instead of relying on memory, paper notes, or a crowded general calendar, I can arrange regular bills around their due dates and connect them with a broader spending plan. That distinction matters. A calendar can tell me that something is due, while a budget can help me understand whether the payment fits comfortably into the month.
A realistic example is a household with rent, utilities, a mobile plan, insurance, and a streaming subscription all landing at different points in the month. Without a system, I might remember the large payments but overlook a smaller renewal. With Bill Payment Reminder, Budgets, I would set up each obligation separately, review the upcoming sequence, and use the budget view to see how those commitments affect money available for groceries or transport. The benefit is not dramatic automation; it is reducing the mental load of remembering everything.
Best Parts of Bill Payment Reminder, Budgets
Things to Keep in Mind About Bill Payment Reminder, Budgets
I also see value for people whose income arrives on different dates. A bill reminder is more useful when I consider it alongside the timing of incoming money. If several payments cluster before payday, the important insight is not merely that they exist, but that the month needs planning earlier. The app can support that review by bringing reminders and spending intentions into the same routine, even though I would still verify the actual account balance and payment status elsewhere.
The family angle is another practical use case. A shared household often fails to manage bills because everyone assumes someone else is watching them. A central budgeting view can help start a conversation about who handles which obligation and how much room remains for flexible spending. I would use it as a coordination aid, not as proof that a payment was successfully processed. That distinction protects against one of the easiest mistakes in personal finance: confusing a planned action with a completed transaction.
News and Features Related to Bill Payment Reminder, Budgets

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
Setting up reminders without creating clutter
The quality of the experience depends heavily on setup discipline. I would begin with only the bills that genuinely repeat, such as housing, utilities, insurance, memberships, and loan-related commitments. Adding every occasional purchase would turn the reminder system into noise. Once the recurring items are under control, I could add less frequent expenses and use the budget side to prepare for them rather than pretending they behave like monthly bills.
A useful technique is to name entries in a way that answers the question I will have later: “What is this charge, and why does it matter?” A vague label may be fine when setting it up, but a clearer description makes a future review faster. I would also separate essential obligations from optional subscriptions in my own budget categories. That creates a more useful decision point when money is tight: I can immediately distinguish what must be protected from what can be paused or reconsidered.
Don't want to read the full review?
The trade-off is that the app is only as dependable as the information I maintain. If a provider changes a due date, an amount, or a billing frequency, an old reminder can become misleading. I would therefore schedule a short monthly review instead of assuming that recurring entries remain correct forever. This is one of the less obvious realities of reminder apps: the initial setup is not the finished system. A few minutes of maintenance can matter more than adding dozens of categories.
Budgeting that supports decisions, not just recording
Budget tools are most helpful when I use them before spending, rather than only looking back at what has already happened. I would start by reserving room for fixed bills, then estimate variable essentials, and only afterward decide how much is available for discretionary purchases. That order prevents an attractive remaining balance from hiding obligations that have not arrived yet.
Screenshots
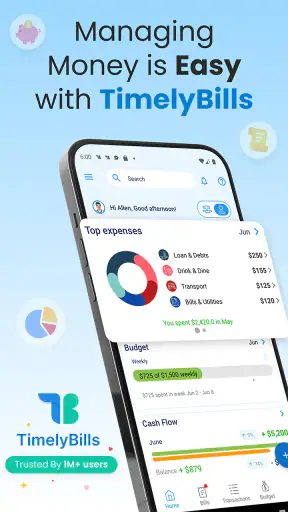
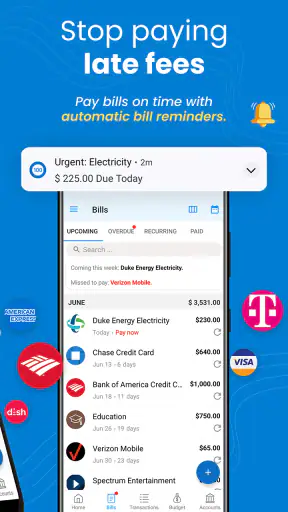
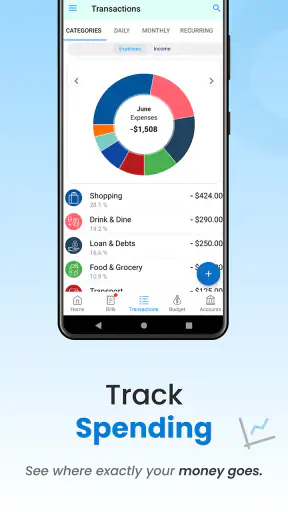
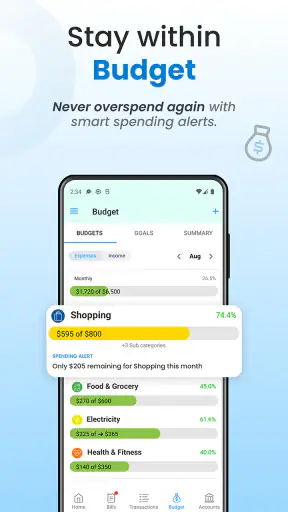
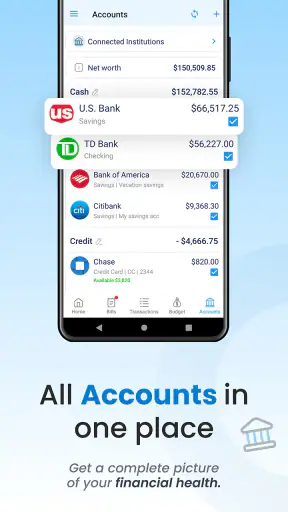
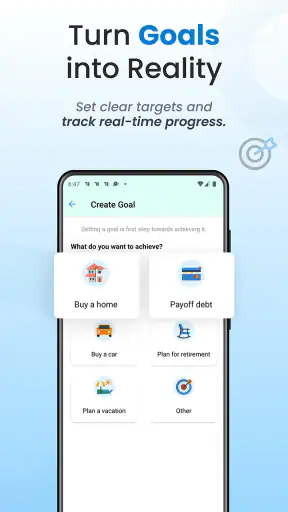
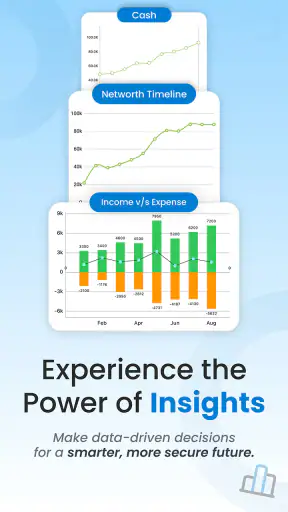
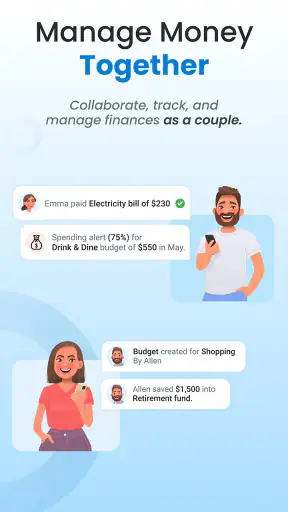
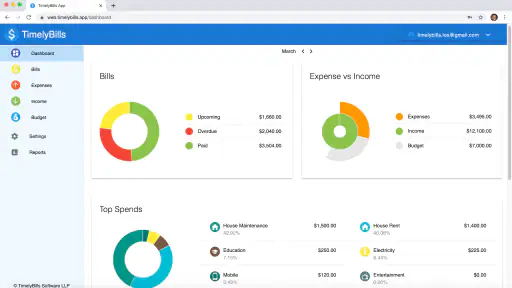
The app’s combination of bill reminders and money-management planning makes this workflow more natural than using a standalone notes app. A note can store a list, but it does not encourage me to connect that list with a spending limit. A general calendar can alert me to a date, but it may not give the same context around the effect on the rest of the month. This is where the app has a clear practical identity.
Still, I would not expect it to replace a detailed spreadsheet for complex financial planning. Someone tracking irregular freelance income, multiple currencies, investments, tax reserves, or business expenses may need more flexible formulas and reporting. For a household trying to avoid missed bills and gain a basic view of spending priorities, the focused approach is more approachable. For advanced analysis, a spreadsheet or specialist finance tool may remain the better choice.
Trust, controls, and moments that deserve care
When I use any finance app, trust is not just about a polished interface. I want to understand what I am entering, what the app is helping me do, and where my own responsibility begins. Bill Payment Reminder, Budgets is easiest to trust when I keep that boundary clear: it helps organize decisions, but I should not treat a reminder as confirmation from a bank, card issuer, utility company, or other biller.
I would begin by entering the minimum information needed for my planning routine. There is no reason to fill a budgeting tool with unrelated personal details simply because a field is available. I would also avoid placing sensitive credentials, card security codes, or banking passwords into notes or descriptions. A reminder label should identify an obligation, not become a storage place for secrets.
Account controls deserve the same attention. Before building a detailed financial history, I would look through the app’s visible settings for options related to account access, notifications, stored information, and any sharing choices. I would make sure I know how to adjust reminders and remove entries that are no longer relevant. If I use the app on a shared device, I would be especially cautious about what could be visible in notifications or on-screen summaries.
These are not reasons to reject the app; they are sensible habits for any tool that sits close to personal finances. The important point is user agency. I should be able to decide which bills to track, which budget categories matter, and how much detail to maintain. A useful finance app should support those choices rather than encouraging me to surrender control of the entire financial picture.
Where sensitive information can appear
There are several moments when I would slow down. The first is during account creation or profile setup, because I want to distinguish information necessary for using the service from information that is merely convenient. The second is when adding a bill. A provider name and payment schedule may be enough for planning; sensitive authentication details are not something I would casually enter.
The third moment is sharing the app with family members. Household budgeting can be collaborative, but not every person needs access to every financial detail. I would agree on a limited routine, such as reviewing upcoming obligations and category totals, rather than exposing private account information unnecessarily. If the app offers visible sharing or account controls, I would inspect them before inviting anyone else. If the available choices do not match the level of privacy my household needs, I would keep the app for personal planning or choose a less shared workflow.
Notifications also deserve practical attention. A reminder that reveals a bill name or amount on a lock screen may be harmless in one home and uncomfortable in another. I would check the phone’s notification settings and choose a level of visibility that fits my situation. This is a small adjustment, but it is exactly the kind of user-controlled detail that can make a finance app feel safer in daily life.
Free access and the decision to pay
The free starting point lowers the barrier to testing the basic workflow. I would use that opportunity to see whether the reminder style fits my habits before considering any purchase. The presence of in-app purchases means I would read each upgrade screen carefully and confirm what a paid item changes for my own use. I would not pay simply because a feature sounds more advanced; I would first identify a specific problem that the upgrade solves.
This approach is particularly important for a budgeting app because the value comes from consistent use, not from collecting every available option. If I only need a small set of reminders and a simple household plan, the free experience may be enough. If I manage many obligations or need more room for organization, a purchase could be worthwhile, but I would judge it against the effort saved over several months rather than against a single busy week.
I also appreciate that the app’s age rating is Everyone, but that should not be confused with a guarantee that every financial situation will fit its design. A young adult managing a few monthly bills may find it approachable. A person handling debt negotiations, joint finances with complicated legal arrangements, or business accounting should treat it as a supplementary organizer at most.
Who should use it and who should look elsewhere
I would recommend trying it to someone who regularly says, “I knew the bill was coming, but I forgot the date.” It suits people who want a dedicated place for reminders and a basic budget routine without learning a complicated financial system. It is also a good candidate for households that need a shared vocabulary around fixed costs, upcoming payments, and flexible spending.
I would be more cautious about recommending it to someone who expects automatic banking accuracy, deep investment analysis, or a complete replacement for their bank’s payment tools. A bank app remains the right place to confirm balances, authorize payments, inspect official transaction records, and resolve a failed charge. A spreadsheet may be better for detailed forecasting. A specialized debt or accounting product may be better for complex cases. The best role for this app is the layer between memory and formal financial records.
One of its strongest non-obvious advantages is that it encourages a forward-looking habit. Many people budget by reviewing damage after spending has happened. Pairing upcoming bills with planned spending helps me ask a better question earlier: “What can I safely spend before the next obligations arrive?” That shift can be more useful than a visually impressive report, especially for someone whose main problem is timing rather than a lack of financial knowledge.
Its main weakness follows from the same design. A reminder system can create confidence without creating certainty. I might see a completed-looking plan and still have an incorrect amount, an outdated due date, or an unpaid bill at the provider. I would therefore keep a simple verification step: after making an important payment, I would confirm it through the official biller or bank and then update my personal tracking. That extra step prevents the app from becoming a source of false reassurance.
My cautious verdict
After using it as a planning companion, I see Bill Payment Reminder, Budgets as a practical finance app for people who need structure more than complexity. The combination of reminders, budget planning, payment tracking, and family-oriented organization gives it a clear everyday purpose. Its free entry point makes experimentation easy, while the established audience and strong average rating indicate that many users find the basic idea useful.
My recommendation is to use it as a controlled planning layer, not as the final authority on your money. Keep entries minimal, review recurring details regularly, protect sensitive information, and verify important payments through the official source. Those habits make the app more useful and reduce the risk of mistaking organization for confirmation.
For me, the deciding question is simple: do I need help remembering and preparing for bills, or do I need a complete financial analysis system? If the first answer is yes, this app is worth trying. If the second is yes, I would choose a more specialized alternative and perhaps keep this one only for reminders. That honest boundary is what makes Bill Payment Reminder, Budgets a sensible recommendation for everyday household planning rather than an overpromised solution to every money problem.
Bill Payment Reminder, Budgets FAQ
What is Bill Payment Reminder, Budgets, and what can I use it for?
Bill Payment Reminder, Budgets is designed to help you organize recurring bills, track spending, and plan your monthly finances from one place. You can record expenses such as rent, utilities, subscriptions, loans, and credit card payments, then monitor upcoming due dates and budget limits. It is especially useful if you often manage several payment dates or want a clearer overview of where your money goes.
How does the bill reminder feature work?
After adding a bill, you can usually enter its name, amount, due date, and payment frequency, such as weekly, monthly, or annually. The app then displays upcoming obligations and may send notifications before the due date, depending on your device permissions and selected settings. Reminders are helpful for avoiding missed payments, but you should still confirm that notifications are enabled and that your payment was successfully processed.
Can I create and manage personal budgets in the app?
Yes, the budgeting tools let you set spending limits for categories such as groceries, transportation, entertainment, housing, or personal expenses. As you add transactions, the app can help you compare your actual spending with the amount you planned. This makes it easier to identify categories where you are overspending and adjust your habits before the end of the month, although the accuracy depends on keeping your entries up to date.
Is Bill Payment Reminder, Budgets safe for storing financial information?
The app may contain sensitive details about your bills, expenses, and financial routines, so privacy should be considered before entering personal information. Avoid adding passwords, banking login credentials, full card numbers, or other details that are not necessary for tracking payments. Review the app’s privacy policy, available security options, backup practices, and requested permissions, and use a device lock to provide an additional layer of protection.
Does the app connect directly to my bank or pay bills automatically?
Bill Payment Reminder, Budgets is primarily intended for organizing bills and managing a personal budget, not necessarily for making payments directly. Whether it supports bank synchronization, automatic transaction imports, or payment links depends on the version and region. In most cases, you should expect to enter or update transactions manually unless the app clearly provides an approved integration. Always verify payments through your bank or service provider.











